
Little Rock sits in the Arkansas River valley, and the humidity pools there like it pays rent. Afternoon storms build on Gulf air, hit the ridges, and dump rain on bungalows and ranches that never fully dry out underneath. Summers are heavy. Winters still freeze often enough to surprise a hose bib. The house you own here lives between those two facts, whether it is a shaded place on the ridge or a newer roof in the western hills.
The Quapaw Quarter and the older streets hold plaster, tall windows, and pier-and-beam floors that telegraph every drip. Hillcrest and the Heights put mature oaks over roofs and send stormwater down steep drives. West of downtown the houses open to more sun, with attics that bake and condensers that run for months. South and east, flatter lots hold water against slabs and beds. One city, several ways for a house to get into trouble.
Name the part of town and the part of the house when you call. A ceiling stain under an oak is a different opening sentence from a deductible question after hail on a bare subdivision roof. Cooling that cannot wring out the river air, a crawl space that smells sweet and rotten, a bath floor that gives, a gutter that pours into a cracked bed: pick the real problem. The river will not sort it for you.
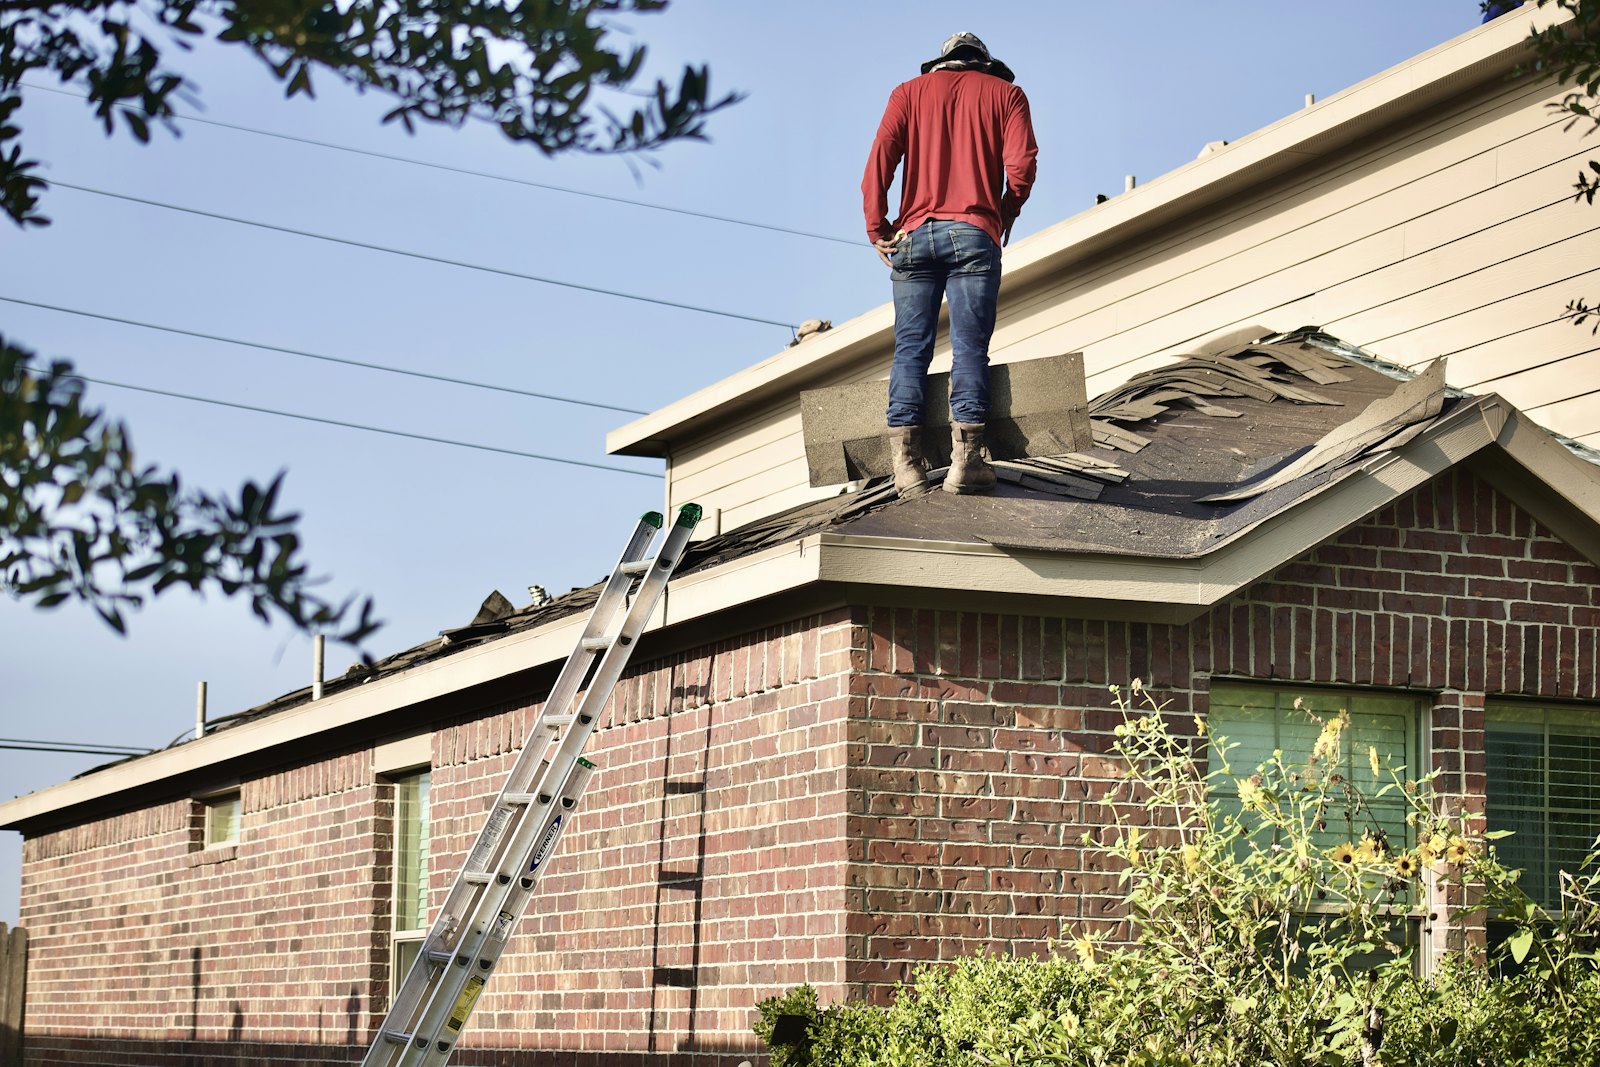
Storms here are regular summer business. Wind throws limbs from willow oak and pine onto ridges. Hail bruises a slope that still looks tidy from the curb. Then the humidity goes to work on whatever the storm loosened, in the deck, in the sash, in the fascia where carpenter ants already like the damp. Waiting for a cool dry week is a pleasant idea and a poor plan in this valley.
Little Rock will stay sticky after the call ends. Walk to the drip edge, look at the ground against the foundation, and notice whether the outdoor unit is keeping up. Have the policy and the deductible in mind if the storm is why you are calling. Then stop browsing your own worries. Pick the trade and call.