
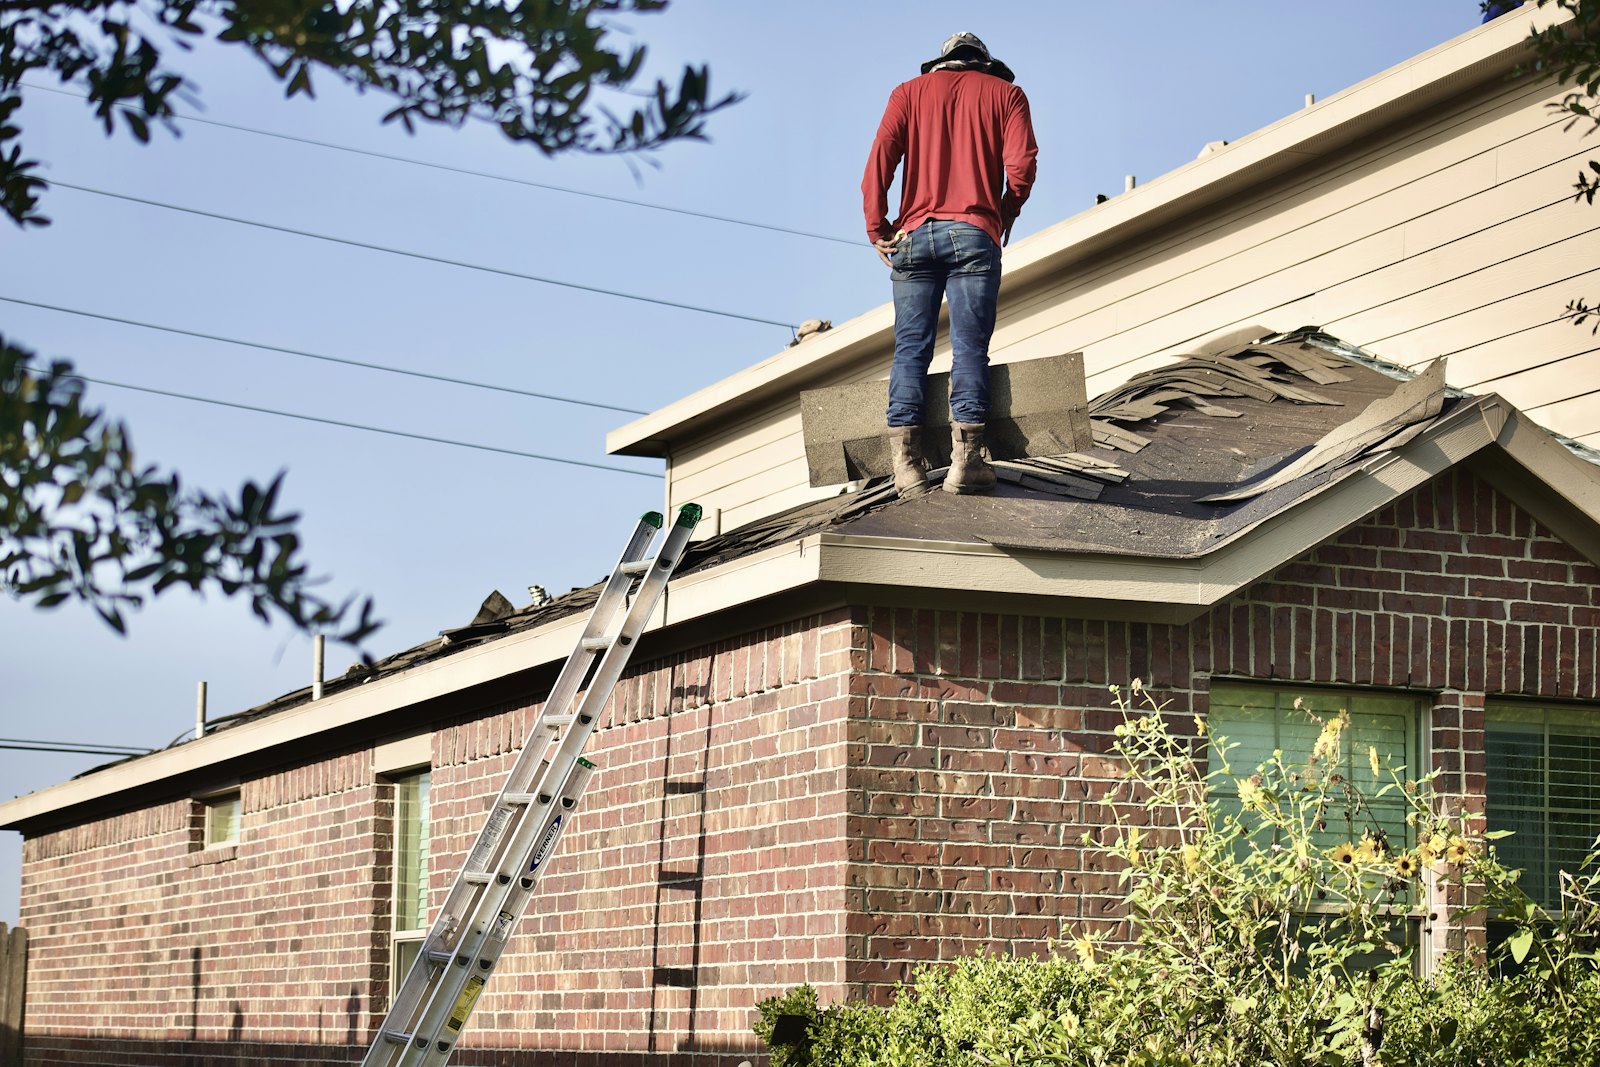
Portland sits west of the Cascades, and the ordinary house is an older wood bungalow that has been rained on for months at a time. Winters are mild and wet. Summers dry out, and then a heat wave finds all the houses that were built with almost no cooling. Moss takes the shaded composition roofs. Fir needles take the gutters. Say the west hills, the close-in bungalows, or the east side before you describe the failure.
Crawl spaces are where these houses store the evidence. A slow leak, a bath fan that never left the building, and rain blown at the siding all end as wood rot in the mudsill or the rim. Carpenter ants follow that soft wood. The west hills shed water at a house on a slope. The east side is a little drier and still wet enough to rot a neglected corner.
The missing cooling stops being a quirk the moment the upstairs will not settle. Many of these houses have a furnace, a few floor vents, and a low roof over the bedrooms. That visit is not the same as a mossed ridge, a gutter dammed with needles, or a crawl that smells sweet and wrong. Do not stack them into one complaint. The trade changes with the failure, and so does the hour you should have called.
Your policy should be read for this wet city, not for a county east of the mountains. The deductible, and what the page does with wind-driven rain, a sudden break, or rot that took a long time, are the lines that matter. Then match a trade to the soft spot in front of you. A stained ceiling, a punky sill, a wet hatch, or a hill that aims water at the house.
Say the part of Portland and the failure in plain words. Say if the crawl is wet, the gutter is packed, the sill is soft, or the upstairs cooked. Have the deductible if a claim is why you are calling. The next stretch of rain will not pause while the plan gets tidier. Pick the trade and call.