
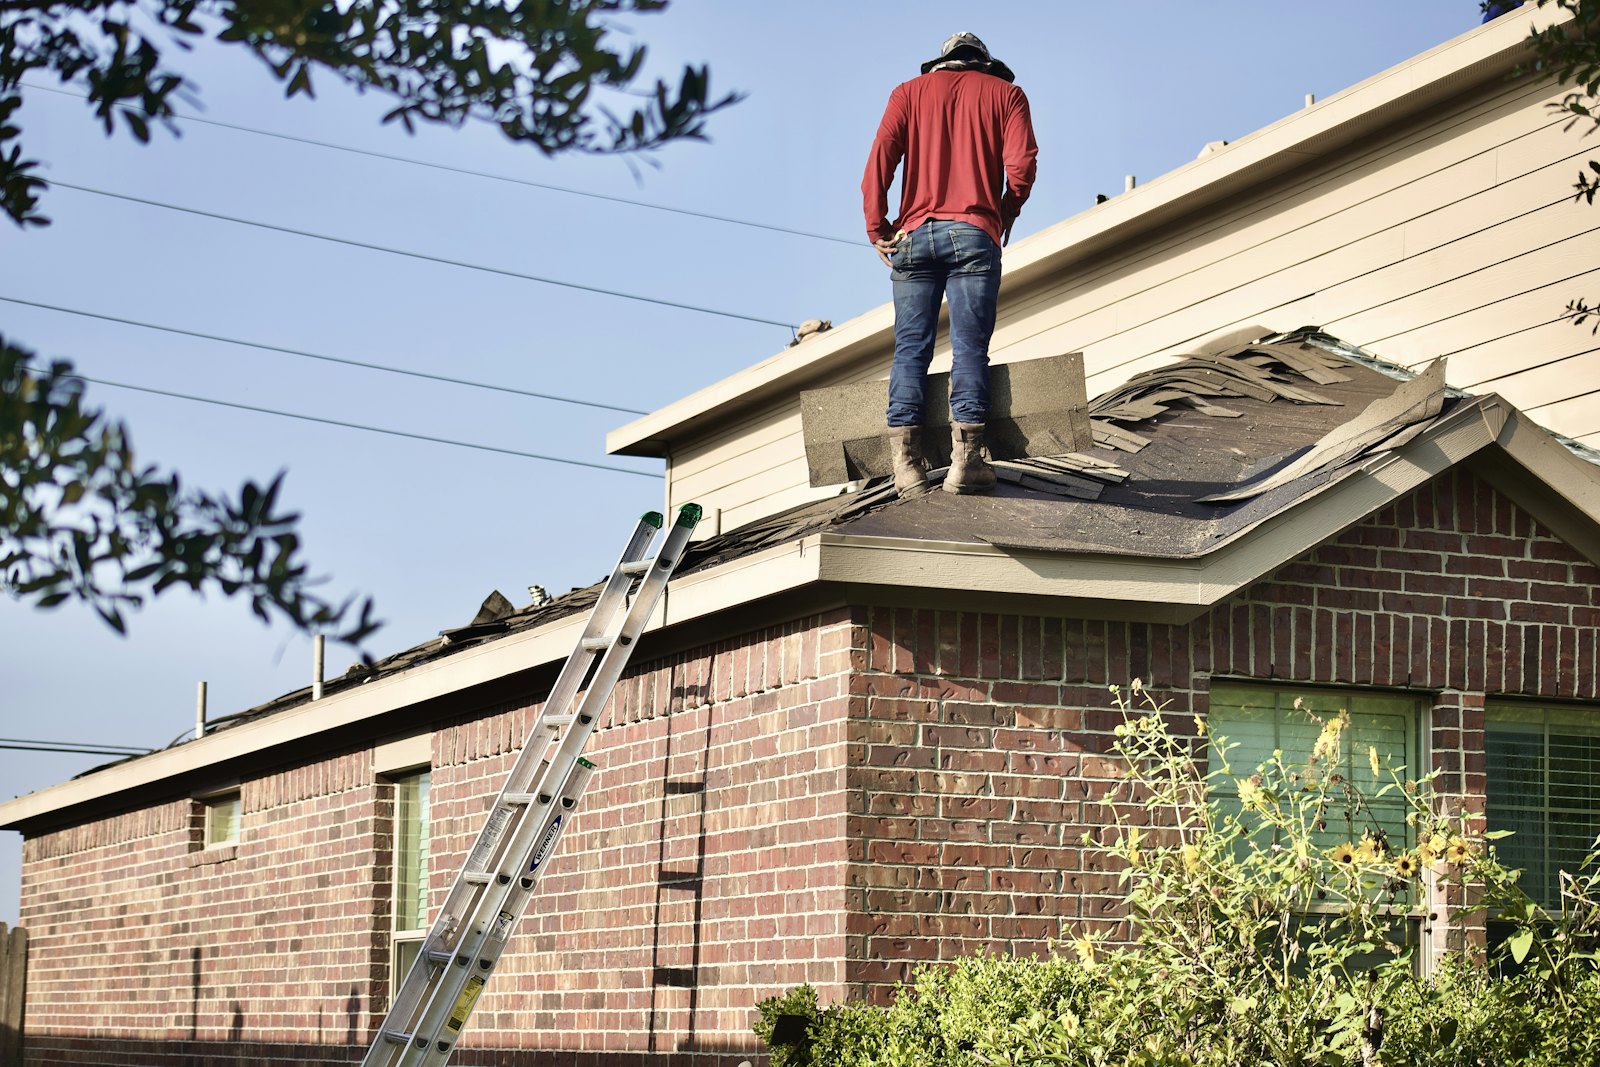
Pennsylvania is an older-house state with a cold winter, a humid summer, and two building habits that should never be swapped. Philadelphia rowhouses are not Pittsburgh houses on hills. A brick row on a flat street shares walls and often a roof that holds water. A house on a western slope is reached by steps, held by a retaining wall, and wet where the hill meets the foundation. Ridge towns and detached houses fill the miles between those cities, with basements, ice, and the same humid summers.
The weather is statewide even when the architecture is not. Freeze-thaw works on brick, on sills, and on roofs. Ice at an eave in the west is still ice. A nor'easter soaking a flat row roof is still a leak. Heavy summer rain finds every lazy grade. The northwest can take a harder lake snow than the southeast. None of that turns a party wall into a hillside, or a city step into a marble stoop. Name the building before you name the trade.
Failures follow the shape. Party-wall water, a cornice, and a stacked bath belong to the row. Retaining walls, steep slopes, and a basement that is buried on only one side belong to the hill. Furnaces and boilers carry the winter in both. Window units fight the humidity. Mice use whichever void the house already has. Your policy question is local too: the deductible and the claim should describe the house that actually got wet.
Call with the shape in the first sentence. Row, hill house, or a detached house that is neither. Then the symptom. If water is moving or the heat is out, say that before the backstory. If this is coverage, have the declarations page and the deductible, and say whether a claim is open. Photos can follow. Do not make the person on the phone guess which Pennsylvania you live in.
The state is wide, and the wrong picture wastes the visit. Say flat or sloped. Say attached or standing alone. Say what failed this week. Pick the trade and call.