
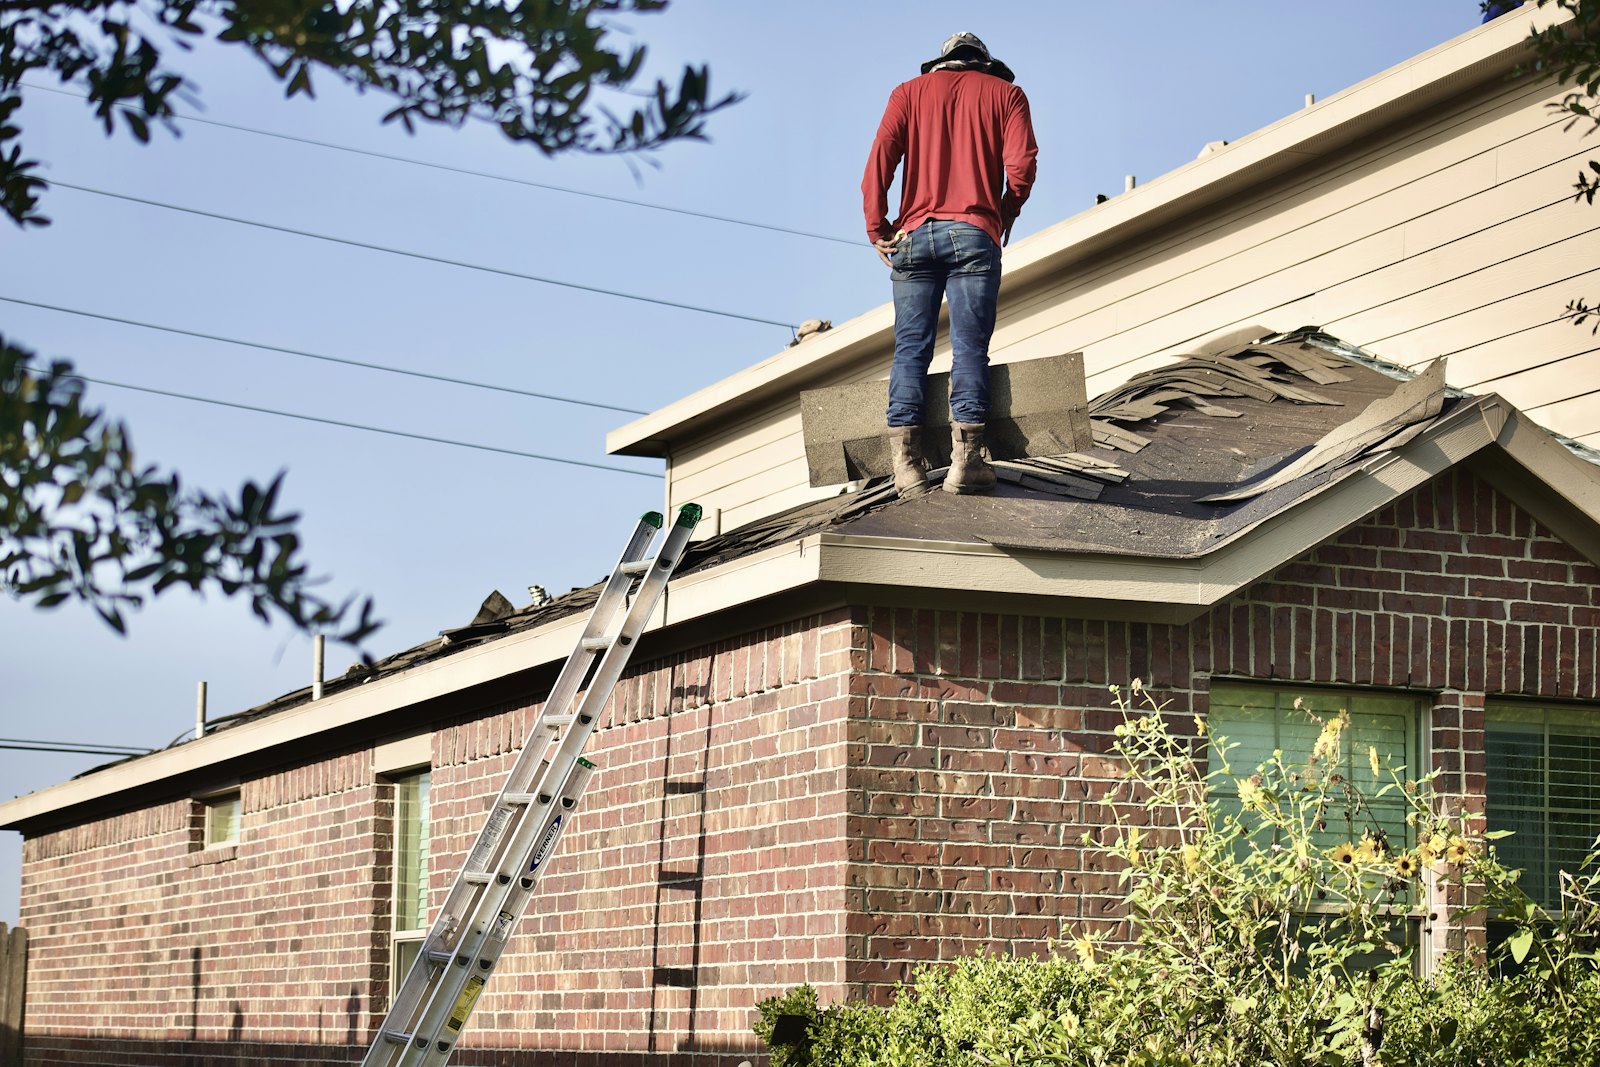
South Dakota wind does not wait for a season. It leans on a house in July the same way it leans on a fence line when the fields are bare. East of the Missouri the gusts cross cropland and whatever shelterbelt is left. West of the river they come off open range and the hills with grit in them. Shingles lift, corners work loose, and a window you latched still whistles.
East river towns and west river ranches do not fail in the same way. A house near Brookings or Watertown takes wind with humidity and thunderstorm rain driven sideways. A house near the Black Hills takes wind that has dried the covering for years and then gets under a loose edge. Pierre sits in the middle of that argument and does not settle it. Name the town before you describe the damage.
People flatten this state into a winter story and then miss the afternoon the ridge cap left. Wind lifts tabs, works siding at the corners, and racks a sash until the meeting rail misses. Dust on the sill and rain stains under a window head are the same force. If you only talk about the furnace, you will walk past the edge of the roof that is already open.
The policy in the drawer has to be read against that force. A wind deductible can stand apart from the rest of the policy, and a dwelling limit is its own figure. Fences, sheds, and a garage door that bowed are where people discover the gap. Match the damage to the trade instead of calling everything a storm. A whistling window is not a roof, and a roof is not a yard.
Say the town and which way the lot faces open country. Say whether tabs lifted, water came in sideways, the heat cannot keep the windward rooms, or a tree is leaning on the eave. Have the deductible handy if this is a claim. South Dakota will send another gust before you finish debating the last one. Pick the trade and call.