
Wyoming is high, dry, and almost never still. The wind that stacks on a house in Rawlins is not the same afternoon as a snow load in the northwest mountains, and the sun on a Casper roof is not a valley problem in Jackson. Elevation, wind, and light work on the same surfaces. Shingles dry out and then lift. Wood checks. Glass takes glare and grit in the same year.
Basins and ranges do not share a season. The Bighorn, the Powder River country, and the stretch through Rock Springs and Rawlins are wind and sun with a hard winter behind them. Sheridan and Cody sit closer to the mountains and a different snow. Laramie is cold, bright, and windy in its own way. A single winter paragraph will not cover a state this exposed. Name the town before you name the damage.
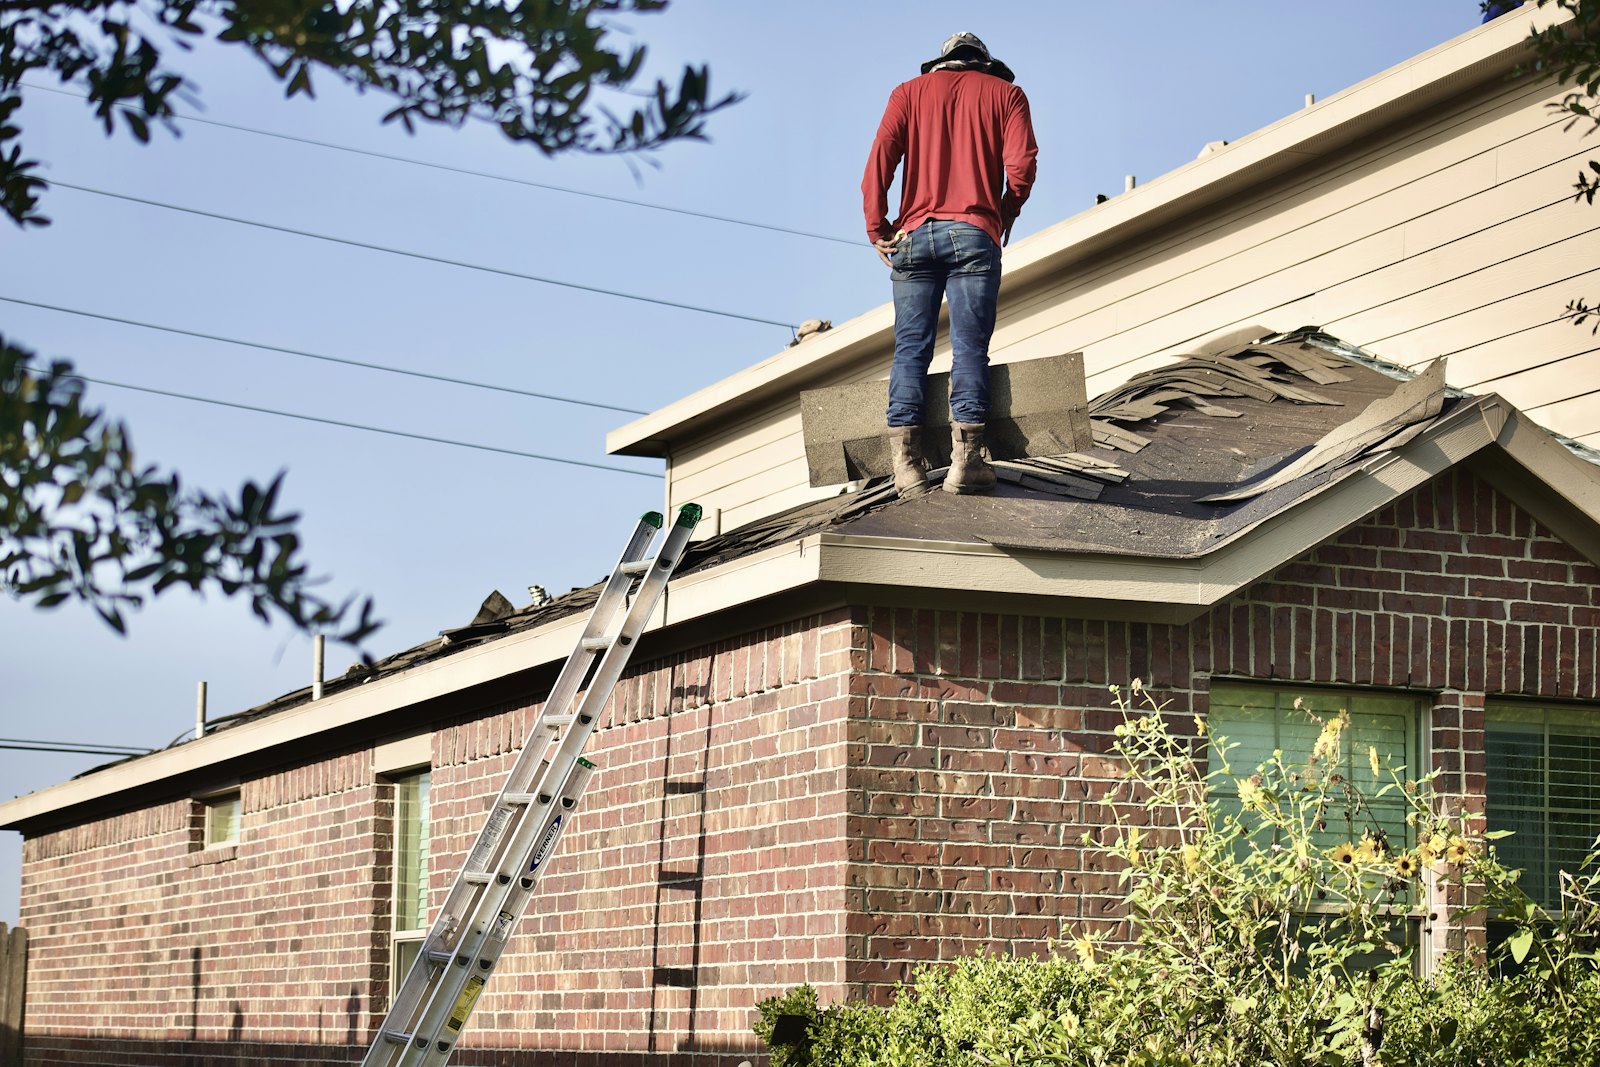
People talk about the cold and skip the sun that cooked the covering and the wind that finished it. That pairing is the ordinary Wyoming failure. A calm morning still shows curled tabs, a whistle at the sash, and dust in every track. Fences, sheds, and a flue cap take the gust whether or not a storm made the news. The house is recording the weather every week, not only in a famous blow.
Your policy has to be read against wind, and against hail where the plains actually get it. The deductible for wind may not match the rest of the page, and the dwelling limit is its own figure where materials travel. Then match the trade. A lifted edge, a pitted pane, a furnace that loses the windward rooms, a well, or a young tree laid over are not one call. Say which surface failed.
Say the town and whether the problem is the wind, the sun-baked shell, the heat, or water where it should not be. Have the deductible if this is a claim. Wyoming will not give the house a still month in which to ignore it. Pick the trade and call.