
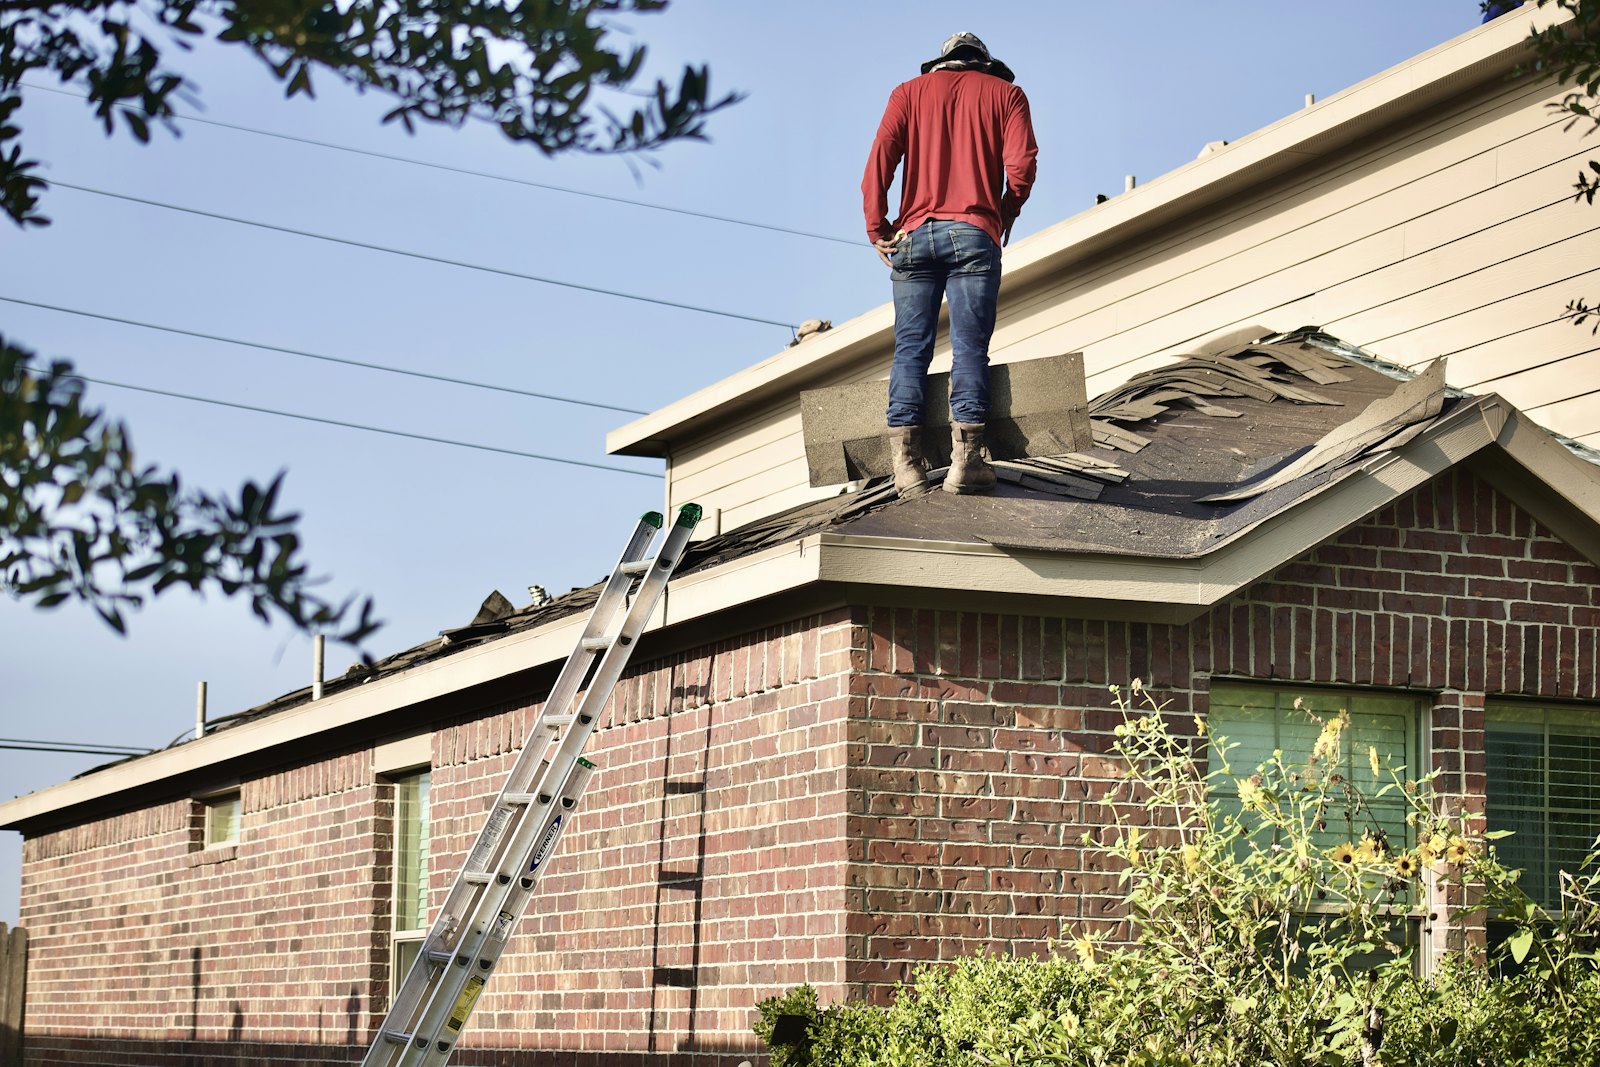
Cheyenne gets wind and hail on the same house, often in the same season and sometimes in the same afternoon. The wind is not a mood. It slams a gate in the cold months and lifts a shingle when the grass is green. The hail is not a rumor. It marks soft metal, bruises the slope that faced the storm, and pits the glass on that side. High-plains sun then finishes whatever the storm loosened.
Older streets near the capitol carry trees, brick, and wood that still take the gust in full. Newer edges on the south and east sit on open prairie, so the hail arrives clean and the wind has a fetch with nothing in it. Both are Cheyenne. A whistling sash on a tree street and a peeled rake on an open lot are the same weather and not the same repair. Do not phone them in as one generic roof.
People elsewhere file this town under winter. Winter is real and it is not the whole damage. Wind works the house every month. Hail writes on it in the warm season, and the wind turns that ice into a sideways strike on siding and frames, not only a straight-down bruise. Look at the windward wall and the roof edge together. The afternoon that did both will not label the parts for you.
Your policy has to tell wind from hail, because the deductibles may not match. Read the declarations page before you decide the loss is too mixed to describe. Dwelling limit, fences, and a detached garage that took the gust are the usual gaps. Then pick the trade: the roof, the glass, a condenser full of dimples, a leak that is not a pipe, or a tree the wind laid onto a bruised slope.
Say which part of Cheyenne and which way the lot faces the open. Say whether ice fell, the edge lifted, or both. Have the deductible if a claim is the reason. The wind does not take a week off because the street is lined with trees. Pick the trade and call.