
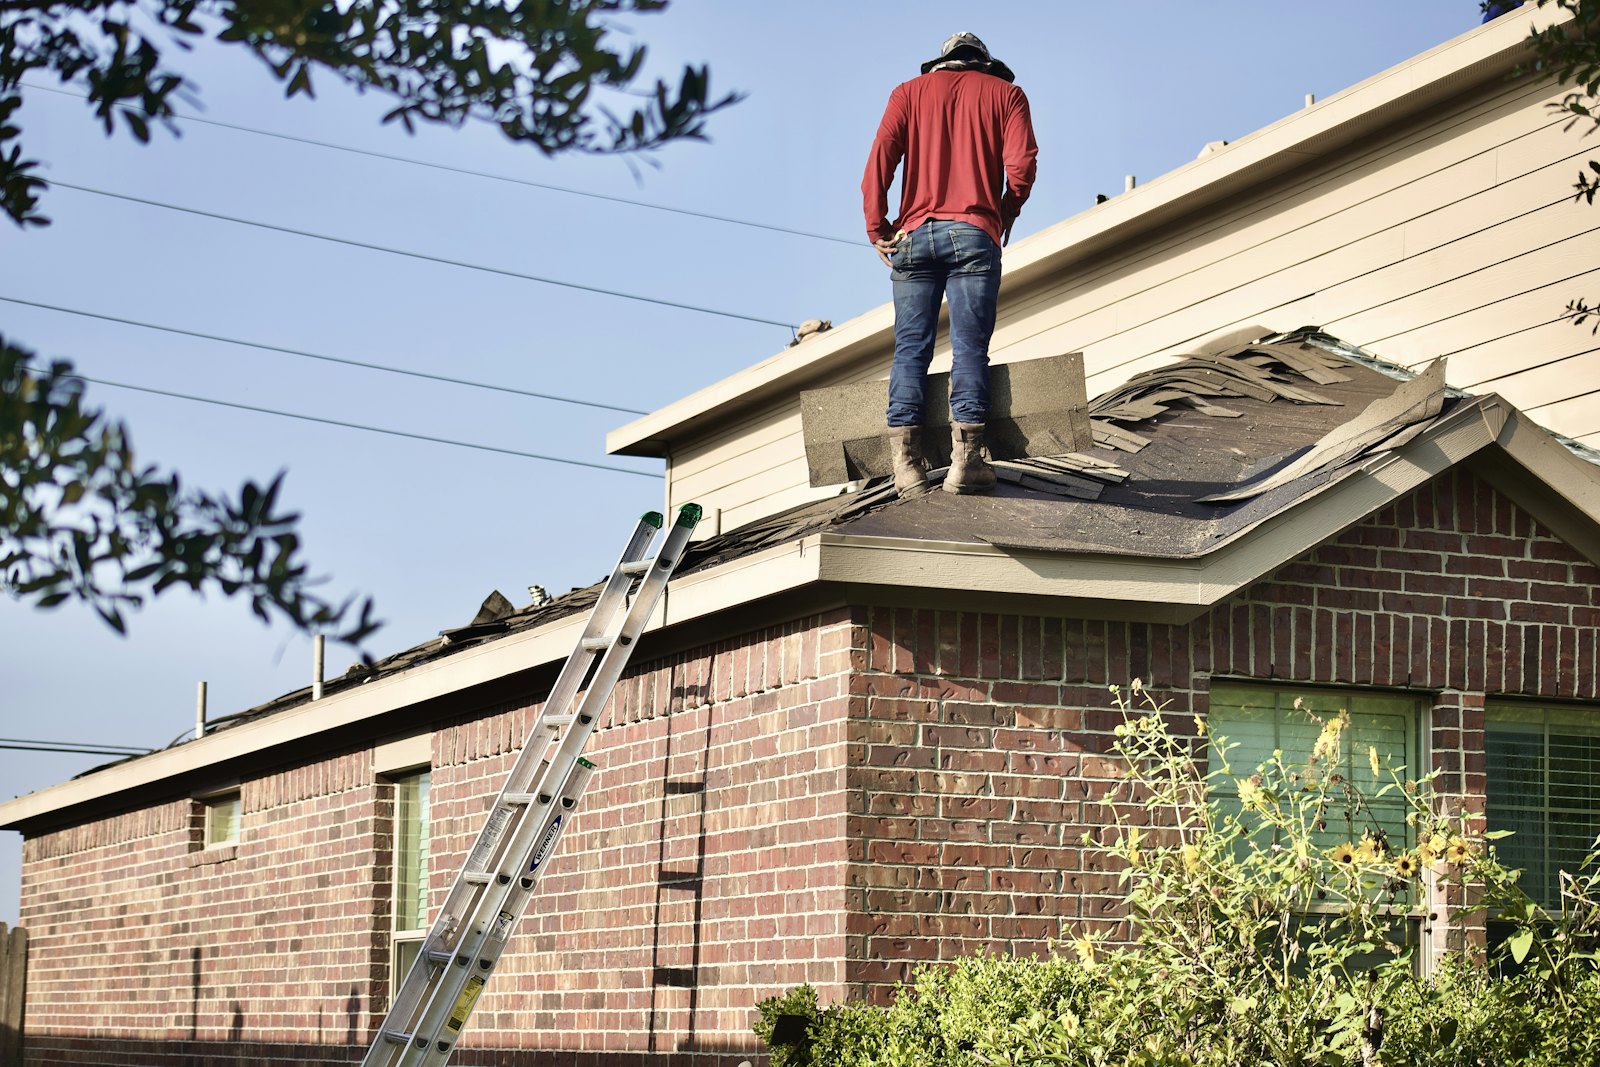
Nebraska takes hail the way other places take rain. Ice falls on the Panhandle, along the Platte, and through the eastern towns, and it does not care whether the house is brick, frame, or new siding on a bare lot. The next morning the gutter holds granules, the flue cap is dented, and the south slope looks bruised even when the ceiling is still dry. The mat can be broken for weeks before a stain shows up on the plaster.
Eastern Nebraska adds humidity to the ice. Storms build over the river valleys, then drop hail on streets where the trees are tall and the basements already worry about water. Western Nebraska is higher, drier, and wider open, so the same ice arrives with grit and a longer run of wind. They share soft metal, asphalt, and glass that record the storm whether or not anyone was home to hear it.
Hail is the standing subject, not a footnote you save for a bad summer. Heat cooks a bruised shingle. A later freeze finds the crack the ice left in a fitting, a sash, or a chimney cap. Mice use the gap a limb opened at the eave. The yard comes back uneven, because ice shreds one side of a lot and leaves the other.
The policy in the drawer is part of the same afternoon. A wind and hail deductible can sit apart from the rest of the policy, and the dwelling limit is its own figure, not a guess borrowed from a similar house. Read what is covered, what is left out, and what you would claim. Then match the damage to the trade. A pitted window is not a furnace call. A condenser with fins mashed flat is not a landscaping call.
Say the town first. Say whether ice fell, water is where it should not be, the glass is scarred, or the outdoor unit looks chewed. Have the deductible in front of you if this is a claim, and have the slope, the room, or the yard in mind if it is the building. Nebraska will hand you another storm before the last one is fully forgotten. Pick the trade and call.