
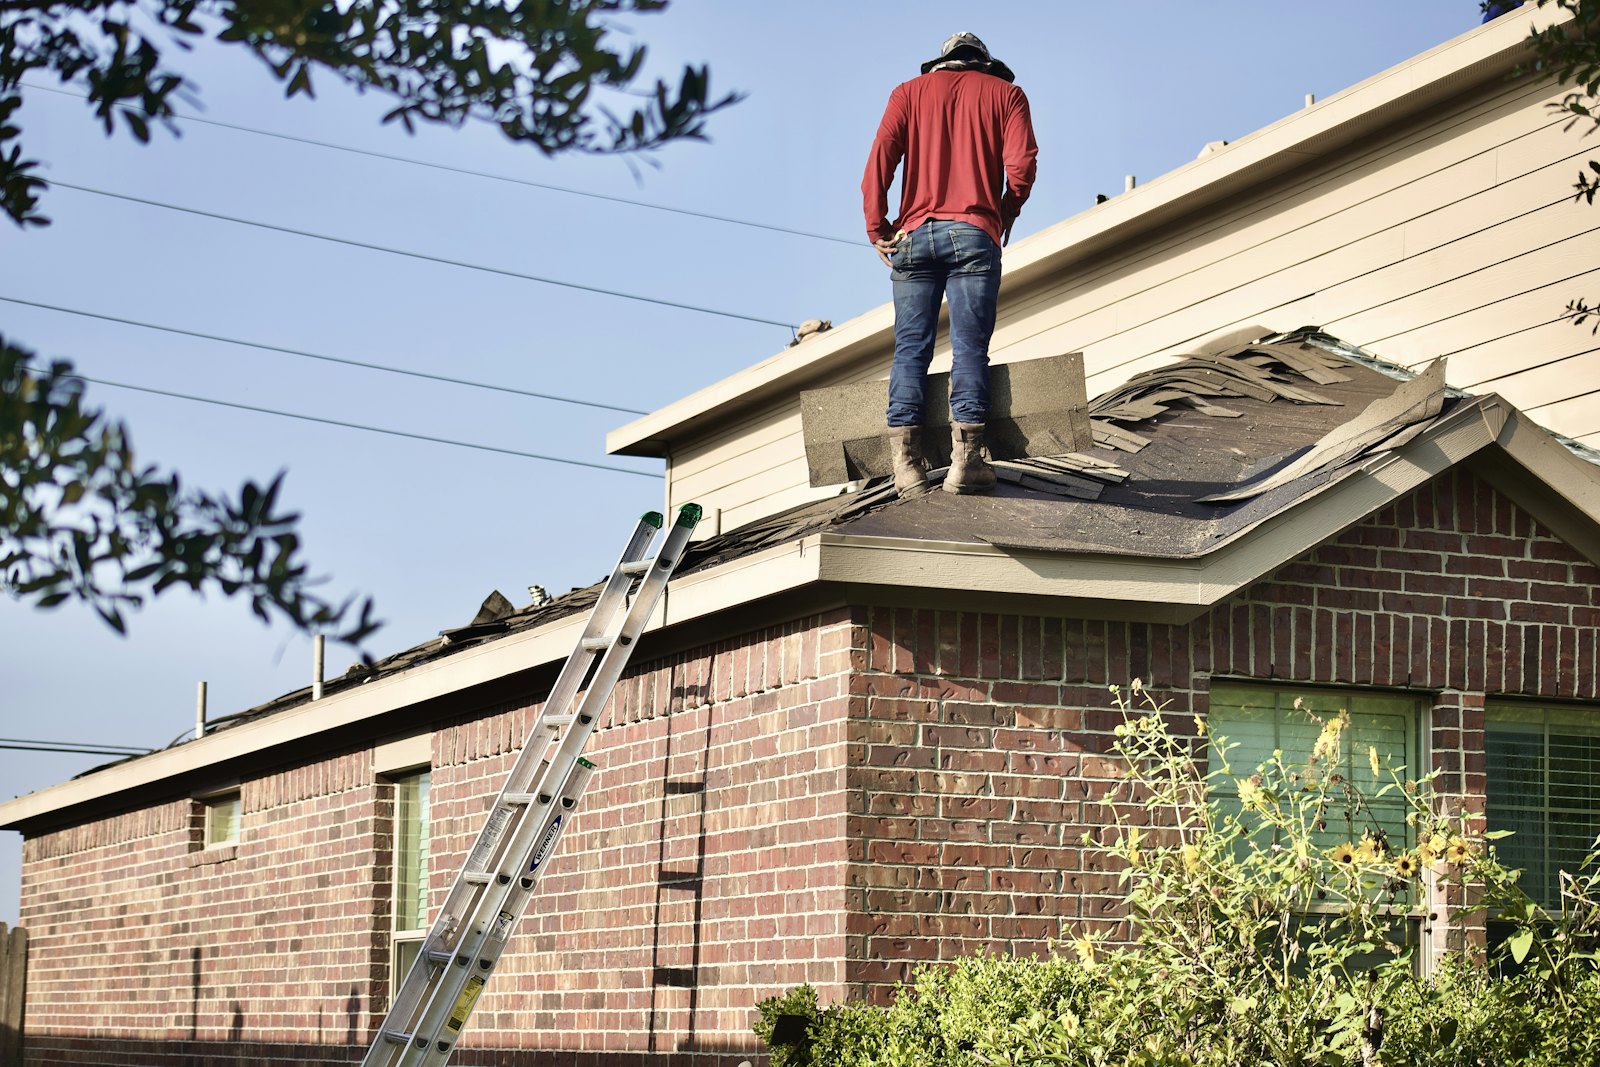
Dallas takes hail like a spring appointment and a hard freeze like a guest who stays a night or two. Supercells bruise shingles, crack skylights, and pit the metal over porches. That short cold can split a hose bib or stall a heater that has sat since the last brief winter. Black clay still shifts under the slab when the rains quit, but the damage people name here is ice from the sky and ice in the line.
Older blocks in East Dallas and Oak Cliff still hide supply lines in attics and on exterior walls of pier-and-beam cottages. A freeze that would be ordinary farther north finds those lines unprotected. Newer two-story roofs north of downtown collect hail in valleys, dormers, and pipe boots you cannot judge from the curb. Red oaks drop limbs when ice loads them for a single night. None of this is a gulf flood story, and it should not be told like one.
The hot season still cooks attics and runs the cooling equipment hard, and the clay under a slab will open a crack in tile or stick a door when it dries. Those are Dallas problems too. They are just not the ones that empty a gutter of granules after a spring storm or stain a ceiling on the morning after a thaw. Sort the failure before you sort the trade. A hail roof, a freeze burst, and a thirsty lawn are three different calls.
Walk the slopes you can see safely, the metal accessories, and the ceilings under attic runs. Note whether the condenser fins look beaten and whether the hose bib weeps. If you are opening a claim, read the wind and hail deductible apart from the deductible on other damage, because a bruised roof and a split pipe may not share it. Keep photos before anyone cleans the gutters or closes a ceiling.
Bring the address and a plain account of what the storm or the cold actually did. Name hail, a short freeze, clay movement, or a cooling system that quit in the heat, and do not blend them into one vague disaster. The trade has to match the failure. Pick the trade and call.